Updated September 2026
Need help with New York sales tax filing?
New York Sales Tax FAQ
Yes. New York imposes a 4% statewide sales tax, but nearly every county and city adds its own local rate on top. Combined rates run anywhere from about 7% to 8.875%, with New York City sitting at the top thanks to an extra Metropolitan Commuter Transportation District surcharge.
Yes, if you have nexus in New York, either through physical presence in the state or by exceeding New York’s economic nexus thresholds as a remote seller.
Nothing. Registering for a Certificate of Authority is free, and there’s no fee whether you’re a homegrown business or a remote seller registering solely because of economic nexus.
No. Most food sold for home consumption is exempt. Restaurant meals, prepared food, and certain candy and soft drinks remain taxable.
Not always. Clothing and footwear priced under $110 per item are exempt from the state’s 4% rate, and from local rates in jurisdictions that have adopted the same exemption. Some counties tax clothing regardless of price, so don’t assume a t-shirt is tax-free statewide.
It depends. Prewritten software and SaaS are treated as taxable tangible personal property in New York, which trips up a lot of software companies. Digital goods like e-books, downloaded music, and streaming video, on the other hand, are generally not taxable.
Services are exempt unless specifically made taxable, but New York has a long list of exceptions. A few examples: interior decorating, protective and detective services, and parking. New York City tacks on its own extra list covering things like tanning, manicures, and massage therapy.
Yes. Once a marketplace provider’s combined sales into New York cross the same $500,000-and-100-transaction thresholds that apply to remote sellers, it must register and collect tax on the sales it facilitates.
Returns are due 20 days after the end of the reporting period. Because New York’s sales tax year runs March through February, due dates land on June 20, September 20, December 20, and March 20 for quarterly filers.
Do You Need to Collect and Remit Sales Tax in New York?
If your business has nexus in New York, you’re required to register with the New York State Department of Taxation and Finance, collect the correct sales tax on taxable transactions, and remit what you collect. New York’s baseline rule is straightforward: sales of tangible personal property are taxable unless specifically exempt, and services are exempt unless specifically made taxable.
The details are where things can get messy.
New York Sales Tax Taxability Matrix
The table below is a quick-reference for how common product and service categories are treated under New York sales tax. For a more exhaustive breakdown, check out the New York State Department of Taxation and Finance reference guide.
| Category | Taxable? | Notes |
|---|---|---|
| Groceries | No | Unprepared food for home use |
| Prepared food | Yes | Restaurant meals, soda, candy, bottled water, etc. |
| Feminine hygiene products | No | |
| Clothing and footwear under $110/item | No | Some counties tax clothing regardless of price |
| Prescription drugs and most OTC medications | No | |
| Prewritten software/SaaS | Yes | Treated as taxable tangible personal property |
| Digital goods | No | E-books, downloaded music/video, streaming, etc. |
| Internet access services | No | |
| Most professional services | No | Legal, accounting, consulting, etc. |
| Specific services | Yes | Interior decorating and design, protective and detective services, parking or garaging vehicles, etc. |
| Hotel occupancy | Yes | |
| Admission charges to places of amusement | Yes | |
| Personal services (within New York City) | Yes | Includes tanning, manicures, massage therapy, etc. |
| College textbooks | No | Specifically exempt for enrolled students |
| Items purchased for resale | No | Valid ST-120 resale certificate required |
| Purchases by qualifying exempt organizations/government entities | No | Valid exemption certificate required |
Do You Have Sales Tax Nexus in New York?
Sales tax nexus is the connection between your business and New York that triggers a duty to collect and remit tax. In New York, nexus can be established through physical presence or economic activity.
Physical Sales Tax Nexus
You have physical nexus in New York if your business:
- Maintains a store, office, or warehouse in the state
- Solicits business through employees, independent contractors, agents, or other representatives who sell taxable goods or services on your behalf
- Solicits business through catalogs or advertising along with some additional connection to the state
- Regularly delivers taxable products to New York customers using its own vehicles (at least 12 times a year)
When it comes to physical nexus, it doesn’t matter how much you sell. Even if you only set up shop once a year at a local craft fair, you’re required to register.
Economic Sales Tax Nexus
On the flip side, economic nexus focuses on a business’s financial footprint, and New York is a bit unusual here. Most states require clearing just one economic nexus threshold. New York requires both of the following, measured over the preceding four sales tax quarters:
- Gross receipts from tangible personal property delivered into New York exceeding $500,000, and
- More than 100 separate sales of tangible personal property delivered into New York
Notice that these thresholds are measured against sales tax quarters, not calendar quarters. New York runs its own calendar:
- Quarter 1: March 1 – May 31
- Quarter 2: June 1 – August 31
- Quarter 3: September 1 – November 30
- Quarter 4: December 1 – February 28/29
Clear both the sales and transaction threshold over the preceding four quarters, and you have 30 days to register for sales and use tax collection. After that, you have an additional 20 days before you’re required to start collecting.
Are Marketplace Facilitators Required to Collect and Remit Sales Tax in New York?
Yes. New York calls them “marketplace providers,” and once a provider’s combined sales into New York cross the same $500,000-and-100-transaction thresholds, it’s required to register and collect and remit sales tax on the sales it facilitates.
If you sell exclusively through a registered marketplace and have no physical presence in New York, you don’t have your own collection responsibility. But if you also sell independently—through your own website, for instance—you must count both your independent sales and your marketplace-facilitated sales when determining whether you’ve crossed New York’s economic nexus thresholds. Cross them, and you’ll need to register and file, even though the marketplace is separately collecting on the facilitated sales.
Common Marketplace Facilitators
- Amazon
- eBay
- Shopify Shop App
- Etsy
- Walmart Marketplace
New York Sales Tax Holidays
Unlike states such as Alabama and Florida, New York doesn’t run any sales tax holidays or tax-free weekends. Instead, the Empire State takes a different approach. Where many other states exempt back-to-school items like clothing on an annual, limited basis, New York made the exemption permanent. Clothing and footwear priced under $110 per item are exempt from the state’s 4% sales tax year-round, and many counties and cities adopt the same exemption locally.
Just remember to double-check local rules before you assume that discount is guaranteed. Some counties still tax clothing at every price point regardless of the state exemption.
Filing New York Sales Tax
So you have nexus in New York—now what? Here’s an overview of how to register, collect, and file New York sales tax.
Need help with New York sales tax filing?
How to Register for New York Sales Tax
New York sales tax registration is fully digital. All vendors—including remote sellers and marketplace providers—register through New York Business Express, which requires setting up an NY.gov Business account. Registration is free, and once approved, you’ll receive a Certificate of Authority, which must arrive before you legally make any taxable sales. You’ll also need to choose between a Regular Certificate of Authority (for ongoing sales) and a Temporary Certificate of Authority (for sellers active no more than two consecutive sales tax quarters in a 12-month period).
Want a full step-by-step walkthrough? Our New York Sales Tax Registration Guide covers everything from gathering your documents to submitting your application.
How to Collect New York Sales Tax
New York’s 4% state rate is only the starting point. New York sources sales based on delivery destination; the rate you charge depends on where the customer receives the goods, whether that’s your storefront or the shipping address on their order. Nearly every county and city layers on its own local rate, and the New York City metro area adds a 0.375% MCTD surcharge on top of that, bringing combined rates to roughly 7% up to 8.875%. That means a single product can carry different tax rates depending on whether it’s shipped to Buffalo or Manhattan, so keeping your point-of-sale rates current matters a great deal.
How to File New York Sales Tax Returns
Nearly every vendor is required to file and pay electronically through Sales Tax Web File, which runs on a separate Tax Online Services account from the one you used to register. A return is required for every assigned period—including periods with zero sales—or you’ll face a minimum $50 penalty.
File and pay on time as a quarterly or annual filer, and you get more than just a clean compliance record—you get a small monetary reward too. New York lets timely filers keep a portion of what they collect as a vendor collection credit, worth 5% of the tax reported and capped at $200 per period. Monthly filers and PrompTax participants unfortunately don’t qualify.
Want the full walkthrough, screenshots included? Our New York Sales Tax Filing Guide covers account setup through submission.
When Are New York Sales Tax Returns Due?
New York assigns each vendor an annual, quarterly, or monthly (part-quarterly) filing frequency, based on taxable receipts or the amount of sales tax collected over a year. See the graphic below for a breakdown of each filing frequency and its reporting periods.
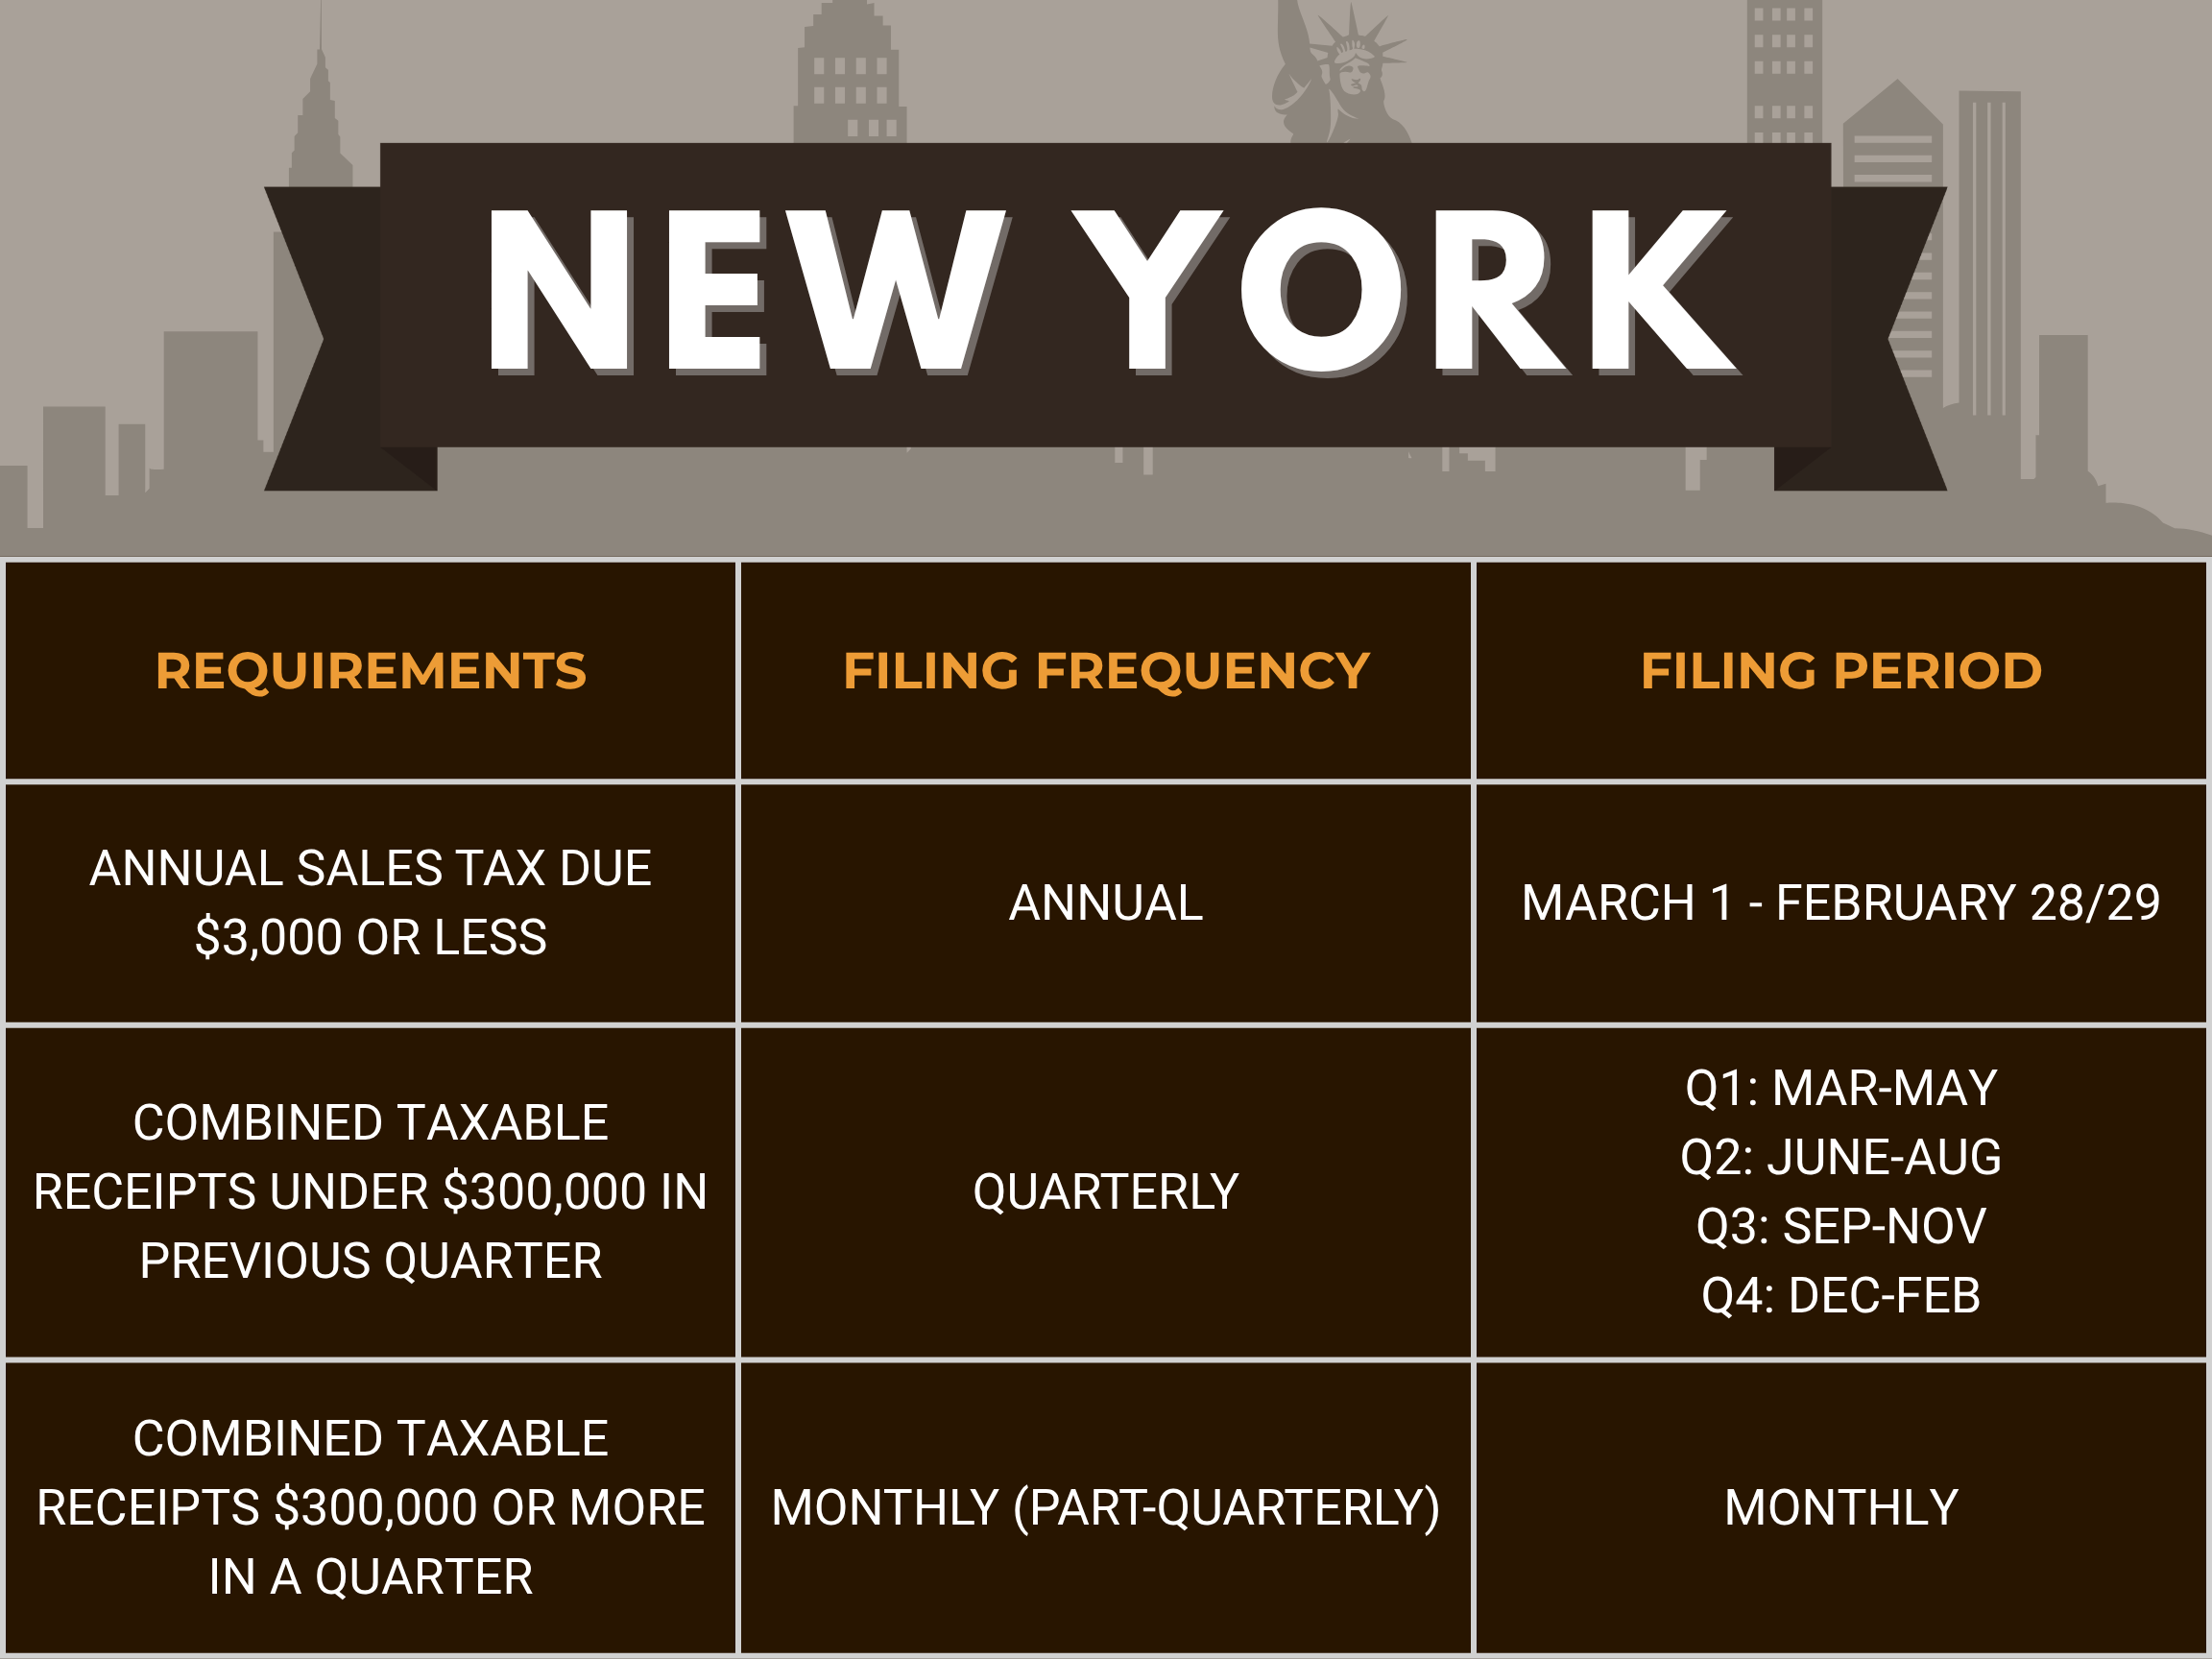
Across every frequency, returns are due 20 days after the end of the reporting period. Because New York’s sales tax year runs from March through February rather than the calendar year, quarterly due dates land on June 20, September 20, December 20, and March 20—annual returns are also due March 20. If the 20th falls on a weekend or legal holiday, the deadline shifts to the next business day.
Larger vendors (generally those with annual sales and use tax liability over $500,000) may also be required to participate in PrompTax, an accelerated payment schedule layered on top of the standard quarterly filing deadline.
Need help with New York sales tax filing?
- New York State Department of Taxation and Finance: Sales Tax Rate Publications
- New York State Department of Taxation and Finance: Do I Need to Register for Sales Tax?
- New York State Department of Taxation and Finance: Quick Reference Guide for Taxable and Exempt Property and Services
- New York State Department of Taxation and Finance: Clothing and Footwear Exemption
- New York State Department of Taxation and Finance: Sales tax requirements for marketplace providers
- New York State Department of Taxation and Finance: 2026 tax filing dates
- New York State Department of Taxation and Finance: ST-120 Resale Certificate
- New York State Department of Taxation and Finance: Exemption Certificates for Sales Tax
- New York State Department of Taxation and Finance: Registration requirement for businesses with no physical presence in New York State
- New York State Department of Taxation and Finance: Business Express
- New York State Department of Taxation and Finance: File online with Sales Tax Web File
- New York State Department of Taxation and Finance: Vendor Collection Credit
- New York State Department of Taxation and Finance: Filing Requirements for Sales and Use Tax Returns
- New York State Department of Taxation and Finance: PrompTax program